FOR BORROWERS
Buying a home in Texas? Start with the numbers.
Explore your estimated payment and cash needed to buy. When you want a closer look, send us your scenario and the questions you need answered.
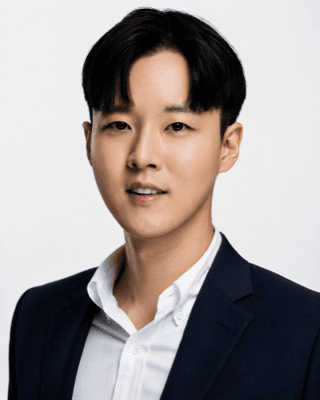 Liam YangNMLS #1709271
Questions, numbers, and the next step. We’ll work through them together.
What you get with Closewiser.
Less overhead in the loan. More time with the loan officer handling it. Here’s what that means when you’re buying a home.
Lower overhead behind your rate.
We use software to reduce repetitive processing work. That means less overhead passed to you, which usually shows in the rate. Bring another lender’s Loan Estimate and we’ll compare the numbers side by side.
Know what you’ll need at closing.
Within 24 hours of your application, we prepare a cash-to-close estimate covering loan fees, title, taxes, insurance, and recording. We update it as the details change, so you can plan beyond the down payment.
A letter backed by a review of your finances.
We review credit, income, assets, and debt before issuing your pre-approval letter. You’ll know what still needs to be resolved. An online estimate alone is not a pre-approval.
Someone who speaks up for your offer.
When you’re competing for a home, we call the listing agent to explain the financial review behind your offer. If they have questions, they can speak with the loan officer who reviewed your file.
Estimate your monthly payment.
Adjust the price, down payment, and rate. See principal, interest, estimated taxes, insurance, and mortgage insurance together. These are planning estimates, not a loan quote.
Auto-fills county tax rate on blur.
Leave at 0 if no HOA.
| Principal & Interest | $2,158 |
| Property Tax(Harris) | $733 |
| Homeowners Insurance | $167 |
| Mortgage Insurance (PMI)— est., applied when down < 20% | $150 |
| Total Monthly (PITI + MI) | $3,208 |
Review or remove your scenario before sending your question.
Estimates only. Actual payments vary by taxes, insurance, HOA, and underwriting terms. Not a commitment to lend. Closewiser — NMLS #1660690. Loan Officer Liam Yang — NMLS #1709271.
ALREADY SHOPPING?
Bring us your Loan Estimate.
Send your Loan Estimate for a personal comparison of the rate, lender fees, and cash to close.
FAQ
Common questions.
Can you help me with a mortgage in Korean?
Yes. We offer consultations, document explanations, and updates in Korean through closing. Lender disclosures and closing documents may be in English. We help you understand what is being requested and what the documents mean.
What should I prepare for our first conversation?
Start with your goal, expected purchase price, down payment, employment, and monthly debts. For document review, common items include pay stubs, W-2s, and bank statements. Self-employed borrowers may also need tax returns and business financials. We give you a checklist for your situation and instructions for sharing documents securely. Please do not send sensitive financial documents through the public contact form.
Does sending an inquiry pull my credit or pre-approve me?
Sending our website inquiry does not pull your credit and is not a pre-approval. Pre-approval requires a review of income, assets, and credit. We explain the documents and credit authorization needed before moving forward.
How long does pre-approval take?
Timing depends on the documents available and the review of your income and credit. We may need additional information before issuing a letter. Tell us your purchase deadline so we can review what is feasible. A pre-approval is conditional and is not final loan approval.
Can I get a mortgage if I'm self-employed?
Self-employed borrowers may qualify for a conventional loan using documented income. Bank Statement loans may offer another option for eligible borrowers. DSCR loans use a property's rental income and are for investment properties, not a home you will live in. Income, credit, assets, and down payment requirements depend on the program.Explore Bank Statement loans
Can you compare a Loan Estimate I already received?
Yes. We compare the loan amount, loan type, term, and rate-lock status alongside the rate, points, lender fees, credits, and cash to close. Taxes, insurance, escrow deposits, and prepaid items need a separate look because estimates can differ. Lower cash to close alone does not mean a less expensive loan.Send your Loan Estimate for review
How long does closing take?
Your contract deadline, documents, appraisal, title work, and underwriting all affect timing. After reviewing your file, we can discuss a realistic timeline. Clear-to-close is the lender's approval to proceed to closing; it is a different milestone from signing and funding.
Want to work through your situation?
Explore your scenario, then share your numbers and questions for a personal review. Sending an inquiry does not pull your credit or qualify you for a loan.